Sealminer DL1 Hydro
Litecoin & Dogecoin ASIC Miner
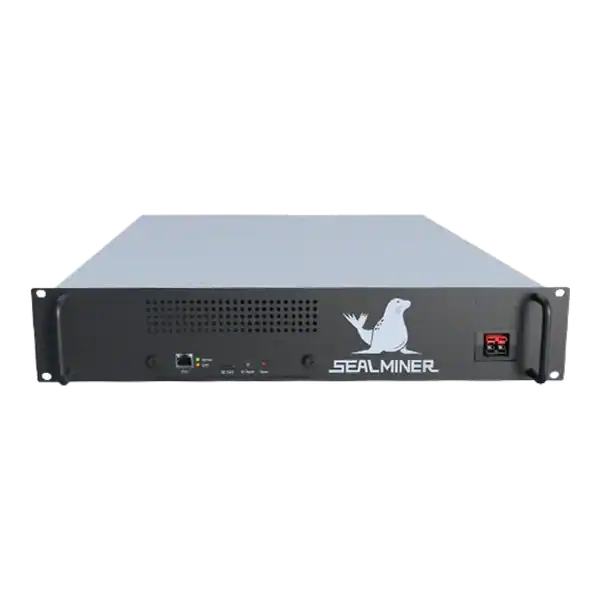

52.5GH
HASHRATE
149W/GH
EFFICIENCY
7823W
POWER
£774.73
EST. MONTHLY
NO PAYBACK
EST. ROI
ASIC equipment finance risk: assess ASIC equipment finance through repayment cash flow, interest, fees, security, personal guarantees, covenants, insurance.
ASIC equipment finance risk depends on a clear operating boundary and evidence that can be checked before money or equipment is committed. ASIC equipment finance converts a volatile operating decision into a fixed repayment obligation.
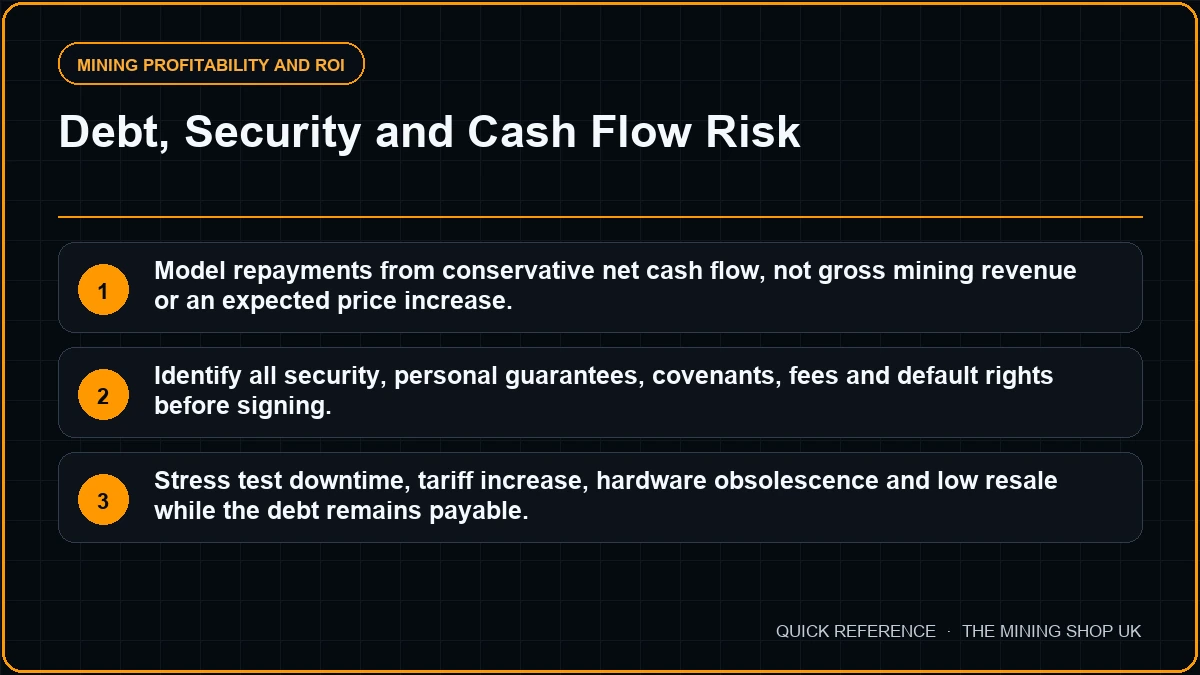
The lender may take security over the machines or other business assets, require insurance, impose covenants and ask directors for personal guarantees. Mining revenue can fall while principal, interest and fees continue.
The borrower should model debt service from conservative cash flow, understand every secured asset and default right, and test whether the financed hardware can be sold or relocated. This article focuses on financing terms rather than whether a particular miner is profitable.
ASIC equipment finance risk: Debt can accelerate deployment. But it removes the option to pause all cash outflow when mining weakens. Understand the complete obligation, protect liquidity and use conservative collateral and revenue values.
A miner is checking ASIC equipment finance risk. Change supplied credentials, use a documented wallet and pool account, set approved backup endpoints and confirm that every endpoint belongs to the intended operator before power is applied.
Record borrower, lender, asset owner, supplier, host and guarantor. Confirm whether title passes immediately and what happens if the supplier or host fails.
Separate hire purchase, finance lease, operating lease, secured loan and unsecured credit. Tax, ownership and termination treatment can differ. So professional advice is needed.
Create a complete payment schedule with deposit, arrangement fees, interest basis, instalments, balloon, early settlement and late charges.
Write the intended outcome before looking at a headline hashrate. A learning device, a useful room heater, a quiet home miner and a commercially productive machine are different purchases. The correct comparison changes when the available circuit, sound limit, heat demand, pool route or expected ownership period changes.
Use a dated decision sheet and keep manufacturer claims separate from measured results. Record the exact model, variant, power supply, firmware and operating mode. Similar product names do not make accessories, voltage, firmware or thermal limits interchangeable.
Match every financed serial and invoice to the agreement. Check whether substitutions, firmware changes, relocation or overseas hosting need consent.
Search registered company charges and get advice on the priority and scope of security. A floating or broad charge may affect assets beyond the financed miners.
Read the guarantee independently. Government guidance warns that a personal guarantee can expose a director’s personal assets if the company cannot pay.
Prefer the manufacturer specification, manual and firmware portal for identity and limits. But treat them as the starting point rather than a promise of site performance. Keep a copy of the pages and files used because support pages, downloads and product revisions can change.
Ask the seller for a serial photograph, condition statement, included accessories and a recent operating record for the actual unit. A generic product image cannot prove board revision, power supply condition, repair history or whether the miner reaches stable accepted work.
Set debt service and liquidity thresholds with named escalation. Keep enough cash for repayment during repair, curtailment and pool settlement delay.
Maintain required insurance and evidence. But check exclusions and lender interest wording. Insurance does not guarantee that every revenue loss or equipment failure is covered.
Control disposal and relocation so an operator cannot breach security terms while trying to improve economics.
A competent person should confirm the electrical route for the real continuous load. Check voltage, protective device, earthing, cable, connector, socket, isolation and ventilation together. Do not assume that a plug physically fitting a socket proves that the circuit is suitable for sustained operation.
Place the miner on a trusted network segment with no unnecessary inbound exposure. Change supplied credentials, use a documented wallet and pool account, set approved backup endpoints and confirm that every endpoint belongs to the intended operator before power is applied.
Calculate debt service coverage from net operating cash after energy, hosting, pool, firmware, repair and tax reserves. Use several downside scenarios.
Compare remaining debt with realistic forced sale value, including condition, shipping and market depth. Invoice price is not collateral recovery value.
Test a simultaneous revenue fall and major repair. If the business can only pay by assuming higher cryptoasset prices, the finance structure is fragile.
Measure power at the wall and compare local hashrate with accepted pool work over a representative period. Local display figures can look healthy while stale shares, invalid work, reconnects or a wrong payout address reduce useful output.
Calculate revenue and cost over a range, not one favourable day. Include electricity, pool fees, auxiliary cooling, maintenance, downtime, conversion costs and hardware value. For a heat-use case, credit only heat that replaces a cost the owner would otherwise incur.
| Risk | Evidence to get | Control |
|---|---|---|
| Revenue falls but instalment is fixed | Downside coverage model | Hold liquidity and cap leverage |
| Guarantee misunderstood | Independent agreement review | Limit or decline exposure |
| Security blocks relocation or sale | Consent and covenant schedule | Approve changes |
| Collateral value collapses | Forced sale evidence | Use conservative advance |
| Insurance requirement not met | Policy and lender clause | Maintain evidence |
Rank each risk by consequence and by the practical ability to detect it before purchase. A low-priced machine with uncertain firmware, exhausted cooling or a weak algorithm market can require more working capital and attention than a newer unit with a higher invoice price.
Set written stop conditions. Examples include an unsafe supply, unavailable official firmware, rejected work above the approved limit, repeated thermal shutdown, no lawful payout route or an energy break-even price below the contracted rate. A stop condition prevents sunk cost from becoming the reason to continue.
Build a month by month model from drawdown to final payment. Insert a site outage, difficulty increase, tariff increase and repair at different points.
Have legal, tax and accounting advisers confirm the agreement structure and governance. Record the board’s reason for accepting the downside and guarantees.
Begin with one unit or the smallest sensible batch. Photograph labels and connections, export the original configuration, note ambient conditions and record the start time. Watch the kernel or system log, board detection, fan behaviour, temperatures, local hashrate, pool connection and accepted work.
Do not declare acceptance from a short dashboard snapshot. Run long enough to expose heat soak, intermittent network faults and pool variance. Retain the test record with the invoice, serial number, firmware file and any seller correspondence so a later repair or warranty question has a clear baseline.
The checklist is deliberately evidence based. Marketing language such as home friendly, efficient or profitable has no fixed meaning without a measured operating mode and a real site boundary. The record should make it possible for another competent person to reproduce the decision.
ASIC equipment finance risk: Debt can accelerate deployment. But it removes the option to pause all cash outflow when mining weakens.
Record borrower, lender, asset owner, supplier, host and guarantor. Confirm whether title passes immediately and what happens if the supplier or host fails.
Match every financed serial and invoice to the agreement. Check whether substitutions, firmware changes, relocation or overseas hosting need consent.
Set debt service and liquidity thresholds with named escalation. Keep enough cash for repayment during repair, curtailment and pool settlement delay.
Debt can accelerate deployment. But it removes the option to pause all cash outflow when mining weakens. Understand the complete obligation, protect liquidity and use conservative collateral and revenue values. No invoice discount compensates for finance terms the business cannot survive.
Use The Mining Shop UK tools and support pages to compare the exact hardware against your real electricity, installation, pool and operating constraints before ordering or commissioning it.
Model repayments from conservative net cash flow, not gross mining revenue or an expected price increase. Identify all security, personal guarantees, covenants, fees and default rights before signing.

Build a five-year ASIC replacement calendar from efficiency gap, tariff, failure rate, parts, firmware, resale, network scenarios and capital gates.
Build ASIC profit forecast ranges using base, downside and severe cases for accepted hashrate, energy, uptime, difficulty, reward, fees, price and repairs.
Compare European ASIC mining energy costs using the correct tariff band, taxes, grid connection, curtailment, cooling, contracts and location risks.
Join the ASIC Mining Discussion
Members can read and join the discussion
Log in to read comments from other miners. Create a free account if you would like to ask a question or share your experience.
Membership helps us protect the discussion from spam and keep answers useful.