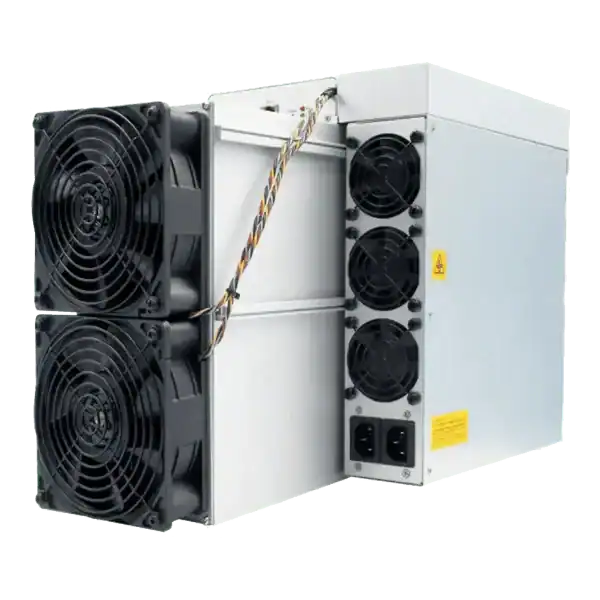
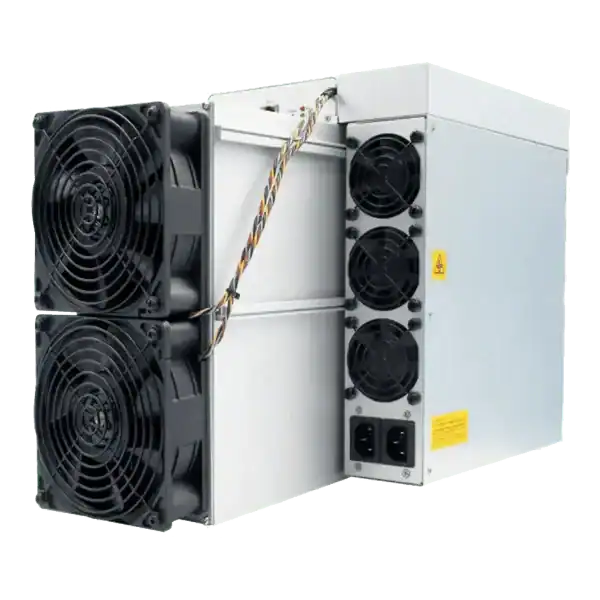
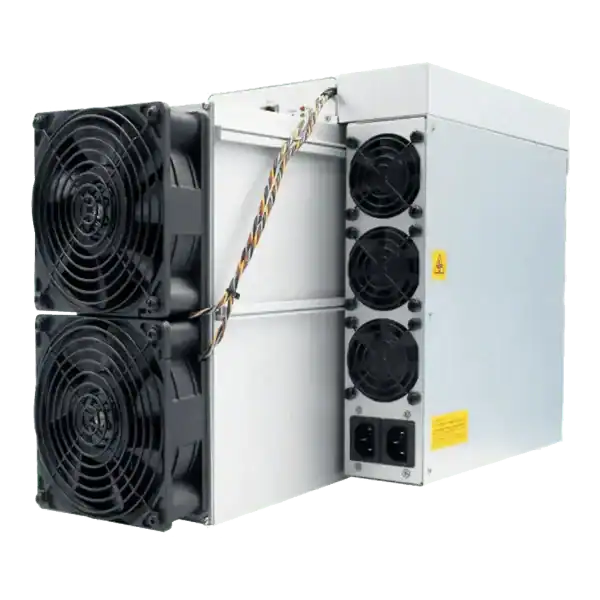
Antminer Z15 Pro
Zcash & Horizen ASIC Miner

860KSOL
HASHRATE
3.3W/KSOL
EFFICIENCY
2838W
POWER
£1417.20
EST. MONTHLY
9
Months
EST. ROI
Understand UK crypto trading tax for miners and investors, including disposals, rare trading status, Section 104 pools, GBP valuations and HMRC records.
Understand UK crypto trading tax for miners and investors, including disposals, rare trading status, Section 104 pools, GBP valuations and HMRC records.
UK crypto trading tax: Separate mined rewards from purchased assets but bring identical assets into the correct pool where required. Reconcile pool income, exchange acquisitions, wallet transfers, fees and disposals.
A UK business owner is checking UK crypto trading tax. Sales, swaps, purchases made with crypto and most gifts can be disposals. Transfers between wallets with unchanged beneficial ownership are normally not.
HMRC says an individual's token dealing amounts to a financial trade only in exceptional circumstances. Frequency alone is not decisive. Where it is investment activity, Capital Gains Tax rules normally apply.
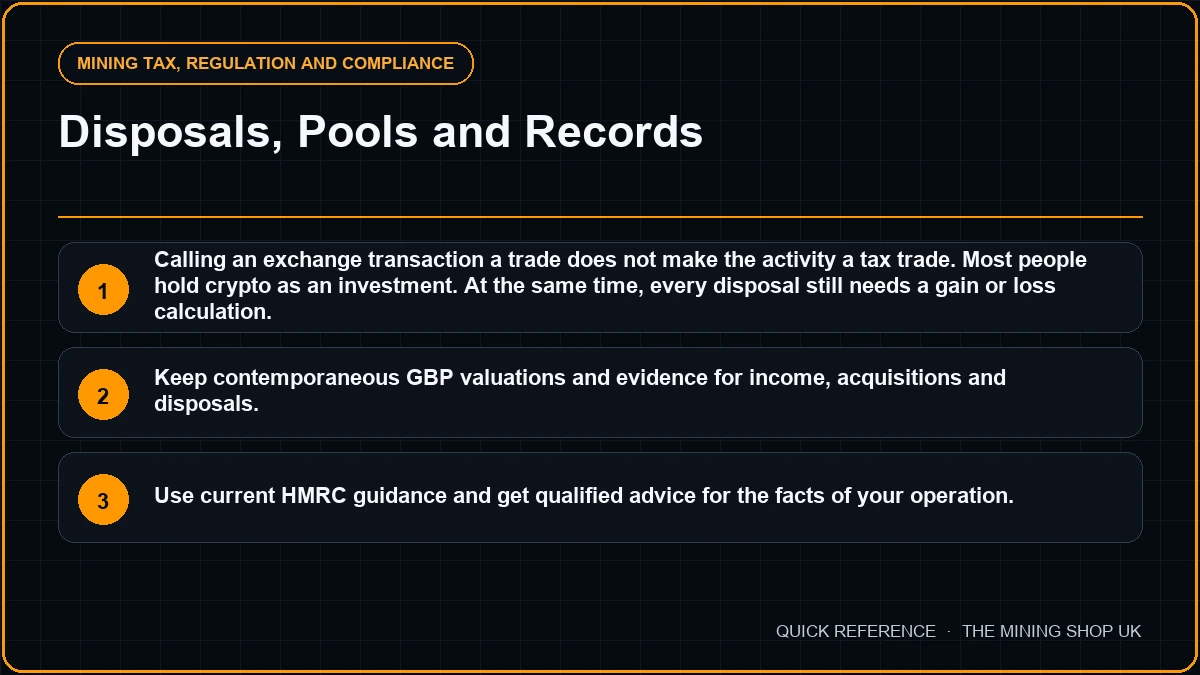
Sales, swaps, purchases made with crypto and most gifts can be disposals. Transfers between wallets with unchanged beneficial ownership are normally not.
Use same-day, 30-day and Section 104 rules for each asset. Do not select FIFO or another method merely because an exchange report offers it.
Separate mined rewards from purchased assets but bring identical assets into the correct pool where required. Reconcile pool income, exchange acquisitions, wallet transfers, fees and disposals.
Tax should not be the only reason for a trade. Consider volatility, liquidity, custody, fraud and market risk and get regulated advice where appropriate. The Mining Shop does not provide investment advice.
Start with the exact equipment, network or service described in this guide. Record the model, firmware, rated and measured wall power, supported algorithm, pool endpoint and the date on which each fact was checked. A product name or broad algorithm label is not enough to prove compatibility.
For mining tax, regulation and compliance, calculate the position using the electricity tariff actually payable, pool fees, rejected shares, expected uptime, cooling load and maintenance. Keep gross revenue separate from operating cost. Repeat the calculation with lower revenue and higher difficulty so the downside is visible before money or equipment is committed.
Confirm that fixed wiring, protective devices, cabling, ventilation and access arrangements suit continuous operation. Use a competent electrician where fixed electrical work is involved. Keep firmware and wallet credentials secure, test with one worker first and retain a written baseline so later changes can be compared with evidence.
Keep dated records of coins received, sterling values at the transaction time, wallet addresses, pool statements, exchange records, fees and directly related costs. A later disposal is a separate event from receiving a mining reward. The treatment can also differ between an individual, a sole trade and a limited company. So the facts and the entity must be identified before a return is prepared.
HMRC guidance distinguishes activity carried on as a trade from activity that does not amount to a trade. Frequency, organisation, risk and commercial character can all matter. Do not assume that a label such as hobby, investment or business decides the answer by itself. Retain the evidence used for each valuation and ask a suitably qualified tax adviser about material or unusual transactions.
UK crypto trading tax: Separate mined rewards from purchased assets but bring identical assets into the correct pool where required.
HMRC says an individual's token dealing amounts to a financial trade only in exceptional circumstances.
Sales, swaps, purchases made with crypto and most gifts can be disposals.
Use same-day, 30-day and Section 104 rules for each asset.
Calling an exchange transaction a trade does not make the activity a tax trade. Most people hold crypto as an investment. At the same time, every disposal still needs a gain or loss calculation. Keep contemporaneous GBP valuations and evidence for income, acquisitions and disposals.
Use current official guidance because tax rules and HMRC guidance can change.
ASIC insurance coverage exclusions: review ASIC insurance exclusions for wear, electrical breakdown, overheating, corrosion, firmware, cyber events, unattended.
ASIC hardware insurance UK: prepare ASIC hardware insurance evidence for UK-owned miners: asset schedule, valuation, site, electrical controls, custody.
Claim VAT on ASIC Miners made simple. Check the UK rules, records, figures and evidence before filing a return or taking professional advice.
Join the ASIC Mining Discussion
Members can read and join the discussion
Log in to read comments from other miners. Create a free account if you would like to ask a question or share your experience.
Membership helps us protect the discussion from spam and keep answers useful.