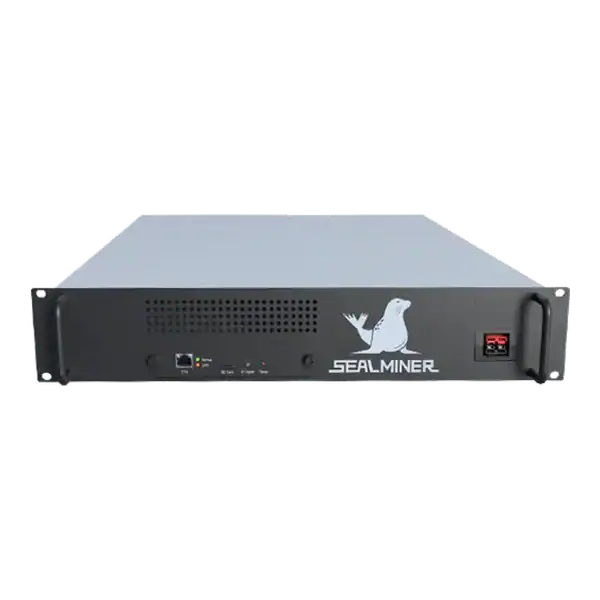
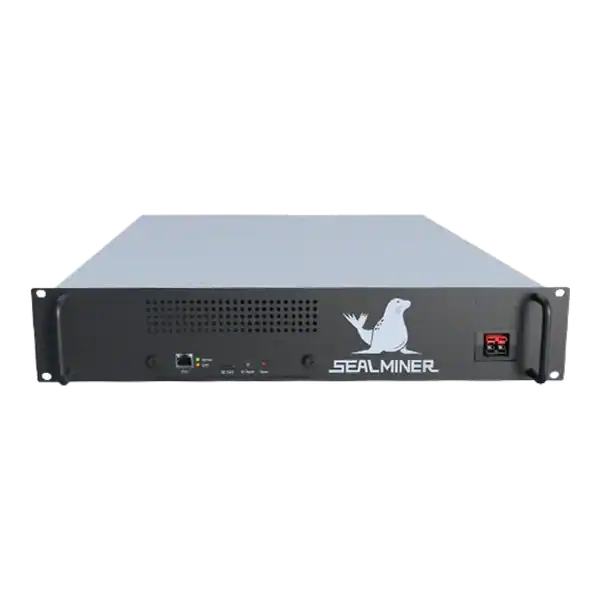
Sealminer A4 Ultra Hydro
Bitcoin & Bitcoin Cash ASIC Miner

886TH
HASHRATE
9.45W/TH
EFFICIENCY
8373W
POWER
£916.50
EST. MONTHLY
NO PAYBACK
EST. ROI
Claim VAT on ASIC Miners made simple. Check the UK rules, records, figures and evidence before filing a return or taking professional advice.

Claim VAT on ASIC miners: Input VAT can normally be deducted where a VAT registered business receives the supply and the cost has a direct and immediate link.
Claim VAT on ASIC miners: HMRC says Bitcoin received by miners is generally outside the scope of VAT because there is an insufficient link between services and consideration.
A UK business owner is checking claim VAT on ASIC miners. If miners and electricity support only that non business activity for VAT purposes, the VAT can be restricted even though the activity produces taxable income for Corporation Tax.
Input VAT can normally be deducted where a VAT registered business receives the supply and the cost has a direct and immediate link to outputs carrying a right to deduct. Keep a valid invoice addressed to the registered entity and evidence of payment and intended business use.
Being a limited company or entering a company name at checkout does not by itself prove the right to deduct.
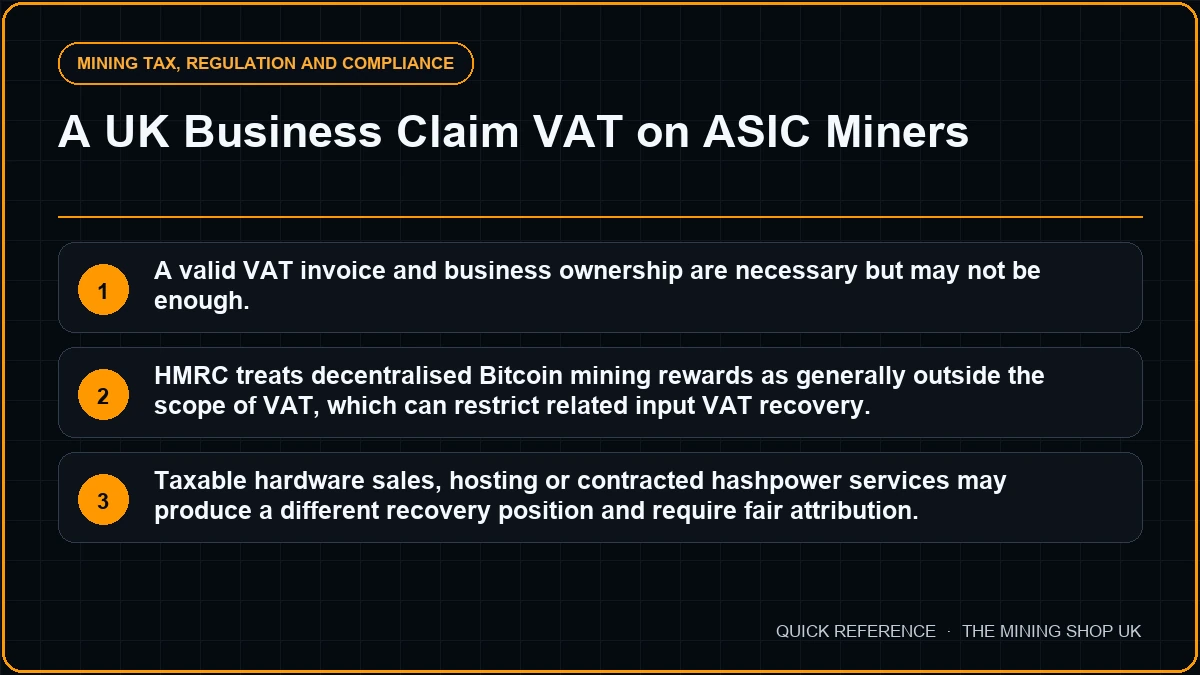
HMRC says Bitcoin received by miners is generally outside the scope of VAT because there is an insufficient link between services and consideration. If miners and electricity support only that non business activity for VAT purposes, the VAT can be restricted even though the activity produces taxable income for Corporation Tax.
Income tax and VAT use different tests. A commercial trade for Corporation Tax is not automatically an economic activity carrying VAT recovery.
A business selling ASIC miners, providing taxable hosting or supplying hashpower under a contract to an identifiable customer may make taxable or overseas supplies carrying a right to deduct. Shared equipment, premises and overheads must then be attributed fairly between activities. Exempt supplies can introduce partial exemption. At the same time, non business activity requires a business and non business apportionment.
An overseas business to business service can fall outside UK VAT under place of supply rules while still carrying input tax recovery if it would have been taxable in the UK. Evidence of the customer’s business status and place of belonging is essential. This route should not be assumed for anonymous or decentralised mining rewards.
The same attribution principles apply to electricity, hosting fees, replacement parts, repair invoices, immersion fluid, pumps and connectivity. Dedicated meters and cost centres make the calculation more reliable. Where one circuit or facility supports multiple activities, document the driver used to allocate VAT.
Import VAT, postponed VAT accounting, customs duty and acquisition documentation are separate from domestic supplier VAT. The importer of record needs the correct evidence. Customs duty is not input VAT. Goods bought under a margin scheme or from a seller that did not charge VAT do not create a recoverable VAT amount simply because the invoice is a business cost.
Private use and use by another entity must be removed or adjusted. A miner at a director’s home can still be a business asset. But the company needs ownership, commercial purpose, metering, access and benefit arrangements that match reality. Changes in use may require later adjustment.
Keep invoices, import statements, asset registers, contracts, meter readings, revenue ledgers, VAT codes, customer location evidence, allocation workings and adviser conclusions. Review the method when the business model changes rather than carrying forward an old percentage indefinitely.
claim VAT on is most useful when it leads to a documented decision rather than a headline comparison.
Claim VAT on ASIC miners: HMRC says Bitcoin received by miners is generally outside the scope of VAT because there is an insufficient link between services and consideration.
Input VAT can normally be deducted where a VAT registered business receives the supply and the cost has a direct and immediate link to outputs carrying a right to deduct.
HMRC says Bitcoin received by miners is generally outside the scope of VAT because there is an insufficient link between services and consideration.
A business selling ASIC miners, providing taxable hosting or supplying hashpower under a contract to an identifiable customer may make taxable or overseas supplies carrying a right to deduct.
A valid VAT invoice and business ownership are necessary but may not be enough. HMRC treats decentralised Bitcoin mining rewards as generally outside the scope of VAT. This can restrict related input VAT recovery.
Rules and official guidance can change. Check the current source before making a decision.

ASIC insurance coverage exclusions: review ASIC insurance exclusions for wear, electrical breakdown, overheating, corrosion, firmware, cyber events, unattended.
ASIC hardware insurance UK: prepare ASIC hardware insurance evidence for UK-owned miners: asset schedule, valuation, site, electrical controls, custody.
Bitcoin mining tax benefits UK business: UK guidance on tax treatment, records, valuations, costs and evidence to retain before filing or taking advice.
Join the ASIC Mining Discussion
Members can read and join the discussion
Log in to read comments from other miners. Create a free account if you would like to ask a question or share your experience.
Membership helps us protect the discussion from spam and keep answers useful.