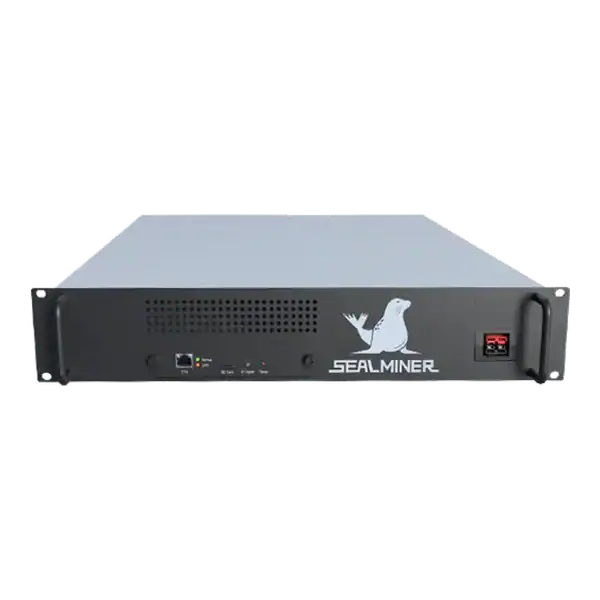
Sealminer A4 Ultra Hydro
Bitcoin & Bitcoin Cash ASIC Miner

886TH
HASHRATE
9.45W/TH
EFFICIENCY
8373W
POWER
£862.14
EST. MONTHLY
NO PAYBACK
EST. ROI
Druk Holding and Investments describes using digital assets, including Bitcoin, to derive value from surplus hydropower while diversifying Bhutan’s energy system.
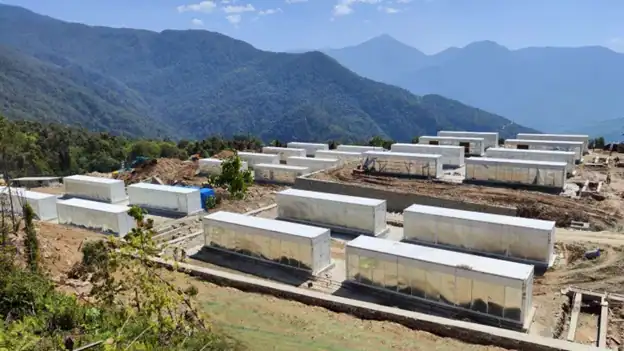
Image: Bitdeer · Original source. Historical construction photograph released in June 2023.
Renewables and heat reuse
Druk Holding and Investments describes using digital assets, including Bitcoin, to derive value from surplus hydropower while diversifying Bhutan’s energy system.
About 5 minutes to read
DHI presents digital assets, including Bitcoin, as part of Bhutan's efforts to gain value from its energy resources and diversify its economy. The setting is very different from a single farm or commercial building. Seasonal river flows, domestic electricity use and export opportunities all affect what power is available and what it is worth.
The value of a national Bitcoin holding cannot be used as a mining return per kWh. It can change after the coins were mined, and may reflect decisions about when to hold or sell them. A site comparison needs the electricity used, mining output, equipment costs and the alternative export value for the same period.
The calculation below uses assumed UK prices to show how the costs fit together. It is our example, not this project’s reported earnings. Replace the inputs with current machine estimates and the costs at your own site.
Illustrative UK calculation
1,000 kWh used by miners, plus 50 kWh for pumps and fans. All amounts in pounds.
Operating contributionBefore equipment and installation costs
£15.901.59p per miner kWh
Here, using the electricity for mining gives up a 5p/kWh export payment. That cost includes the 50 kWh used by pumps and fans. It is the value of an alternative sale, so it is not also charged as a grid electricity bill. The example assumes the generation equipment already exists.
| Mining income | 8p per miner kWh; an assumed rate, not a live earnings estimate |
|---|---|
| Electricity | 5p/kWh × 1,050 kWh = £52.50 |
| Pool fee | 2% of gross mining income |
| Useful heat | 0% of miner electricity = 0 kWh; no heat income assumed |
| Other running costs | £10 per 1,000 miner kWh; an allowance to replace with your own costs |
| Costs still to add | Equipment, installation, finance, tax, depreciation, major replacements and any costs above the allowance |
The contribution is what remains from mining income and useful heat after the stated running costs. It is not net profit: the equipment and other excluded costs still have to be recovered. Pumps and fans use electricity but earn no mining income in this calculation.
| Gross income per miner kWh | Operating contribution |
|---|---|
| 5p | −£13.50 |
| 8p Chart example | £15.90 |
| 11p | £45.30 |
These are two ways to read the same example. Adding equipment costs or a larger maintenance allowance raises the income needed and reduces the electricity price the project can afford.
If the electricity has no export value or other useful destination, removing the export cost improves this example by £52.50. Generator maintenance, equipment costs and any payment to the electricity owner still remain. Heat is given no value here because the source does not establish a usable heat supply.
For an annual estimate, use the miner electricity expected during hours when running makes sense. Scale the contribution by annual miner kWh divided by 1,000, then deduct fixed annual costs. Recalculate if electricity prices, mining income or usable heat change.
Simple payback is the total installed cost divided by positive annual cash contribution. There is no payback under a scenario with zero or negative contribution. The sources reviewed here do not provide the full project accounts needed to calculate an actual payback for this installation.
Evaluate mining alongside export opportunities and seasonal domestic electricity demand.
Separate mined output, purchased assets, realised sales and mark-to-market gains. Obtain site energy use, seasonal availability and alternative export value.
Try your own electricity and heat figures
Compare available miners and dated earnings estimates. Include heat only where you can use it or have a customer for it.
Sources checked on 29 September 2026. Project facts and quotations come from the publications below; the UK calculations and practical assessment are The Mining Shop’s analysis. This article is based on published material, rather than a site visit.
Photographs: Bitdeer (source).

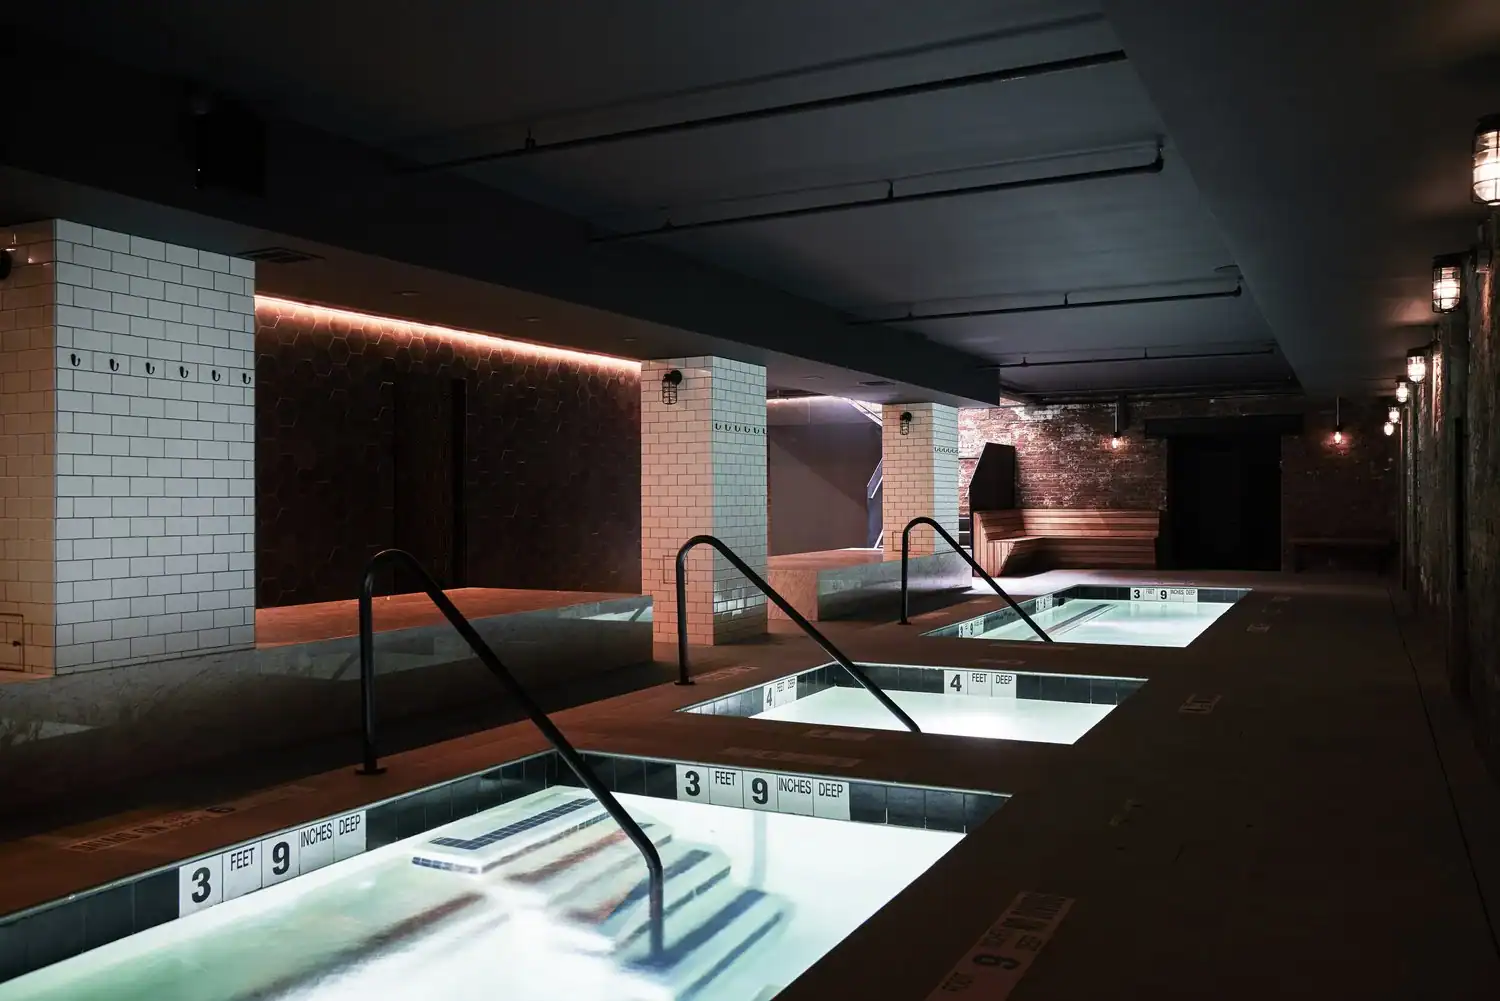
Bathhouse says it began a pool-heating mining pilot in 2022. Its technical explanation describes immersion-cooled ASICs, a dielectric-fluid circuit and heat exchangers that transfer heat into pool plumbing. The comparison is with its previous electric resistance heaters.
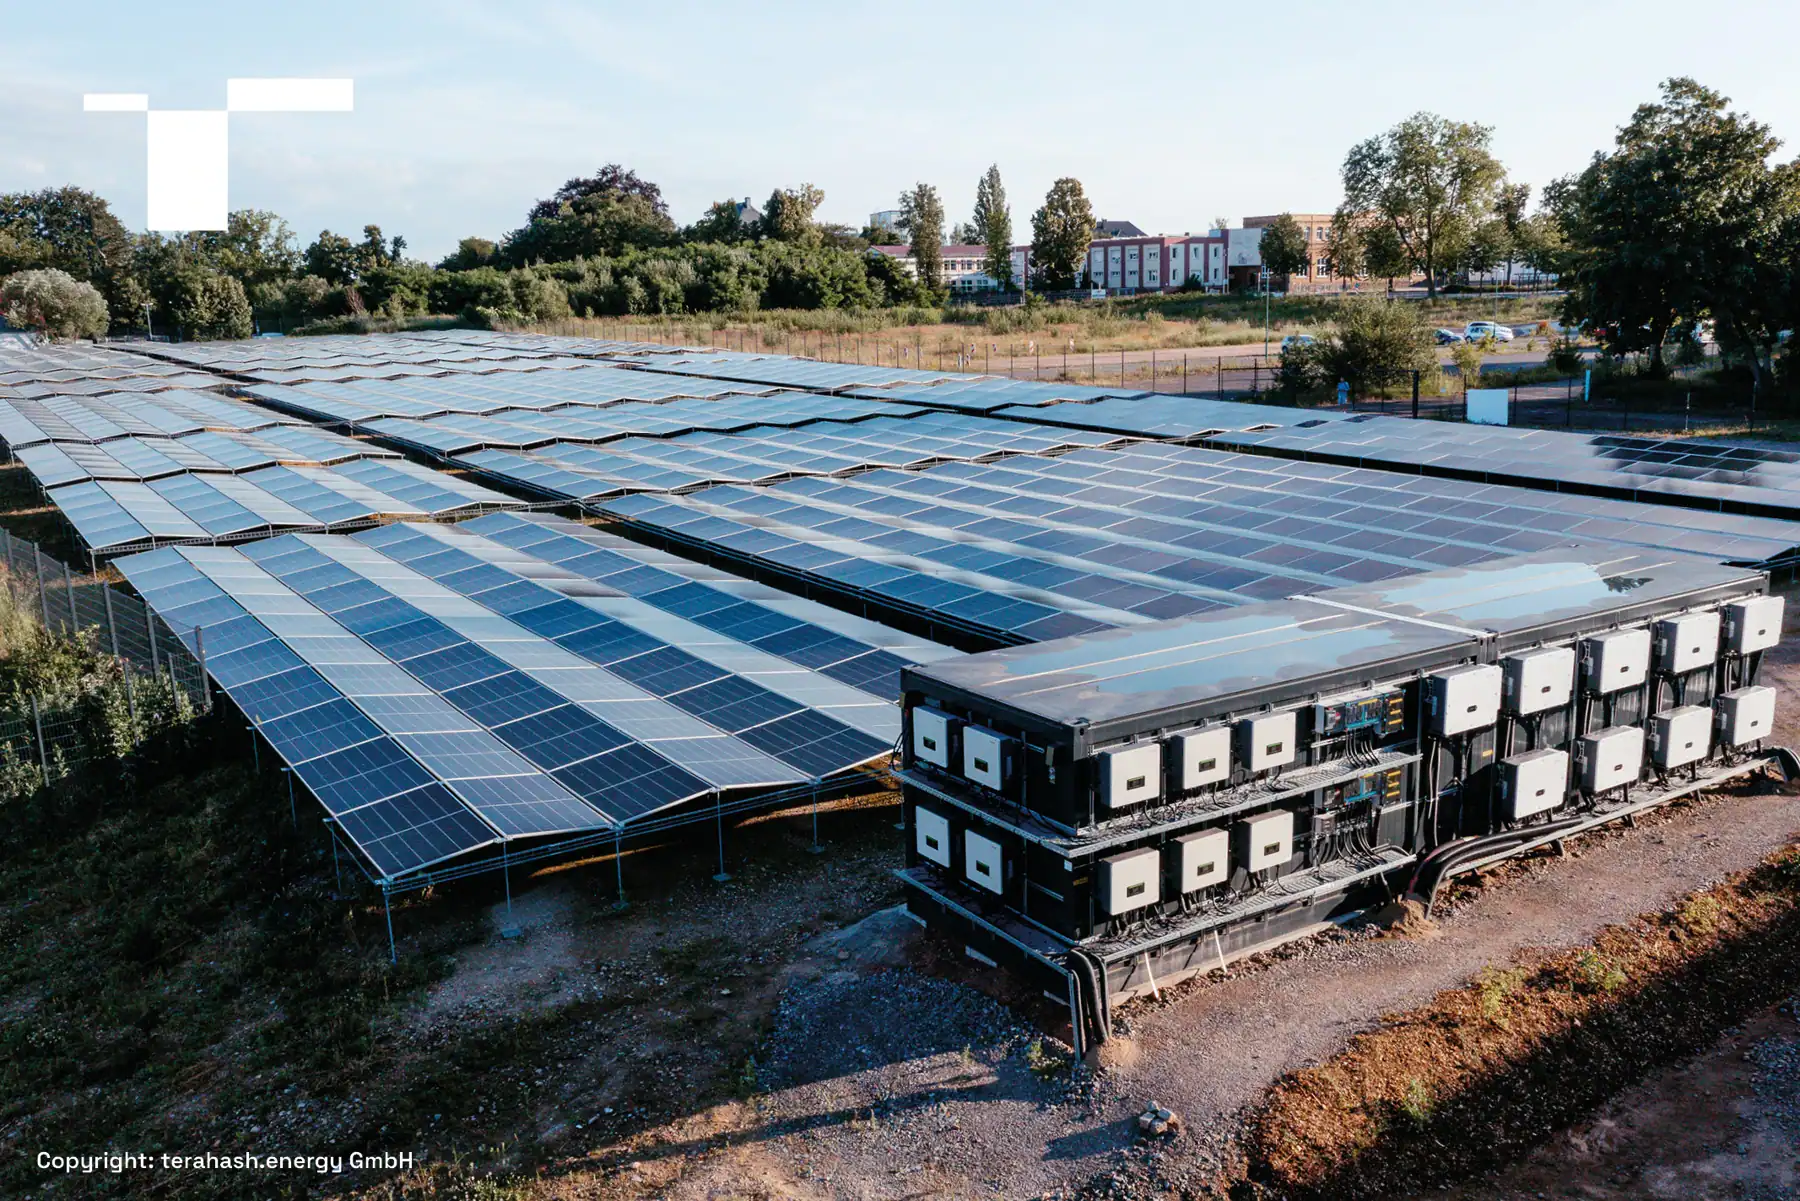
Terahash describes Kläger Group’s Hartha energy park with a 1.6 MWp solar array, a 350 kWh battery and a mining container able to absorb up to 500 kW. The container is intended to buy surplus left by industrial production, with storage and grid export also available.
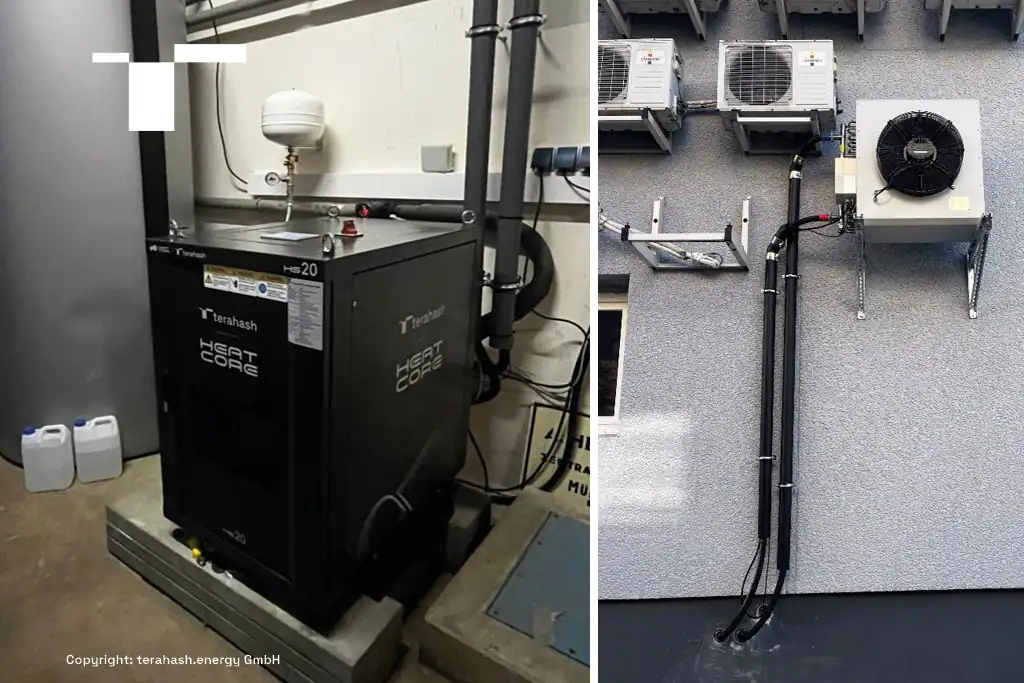
Terahash describes a commissioned system at Nebona’s spice factory: a Heatcore HS20 with two Whatsminer M63 units uses surplus rooftop solar power and supplies hot water to a buffer tank. The existing heating system remains available.
Join the ASIC Mining Discussion
Members can read and join the discussion
Log in to read comments from other miners. Create a free account if you would like to ask a question or share your experience.
Membership helps us protect the discussion from spam and keep answers useful.